Facing a past-due real estate note can feel overwhelming, even for experienced investors and lenders. You put in the time, effort, and capital to build your portfolio, so it is only fair that your investment performs as expected. When a borrower stops making payments, it can create stress and uncertainty. But here is the exciting part. You are not powerless. You have a range of proven legal strategies that can help you take back control and recover what is rightfully yours. With the right approach, you can shift from feeling stuck to taking confident, strategic action.
The Soft Start: Your Demand Letter
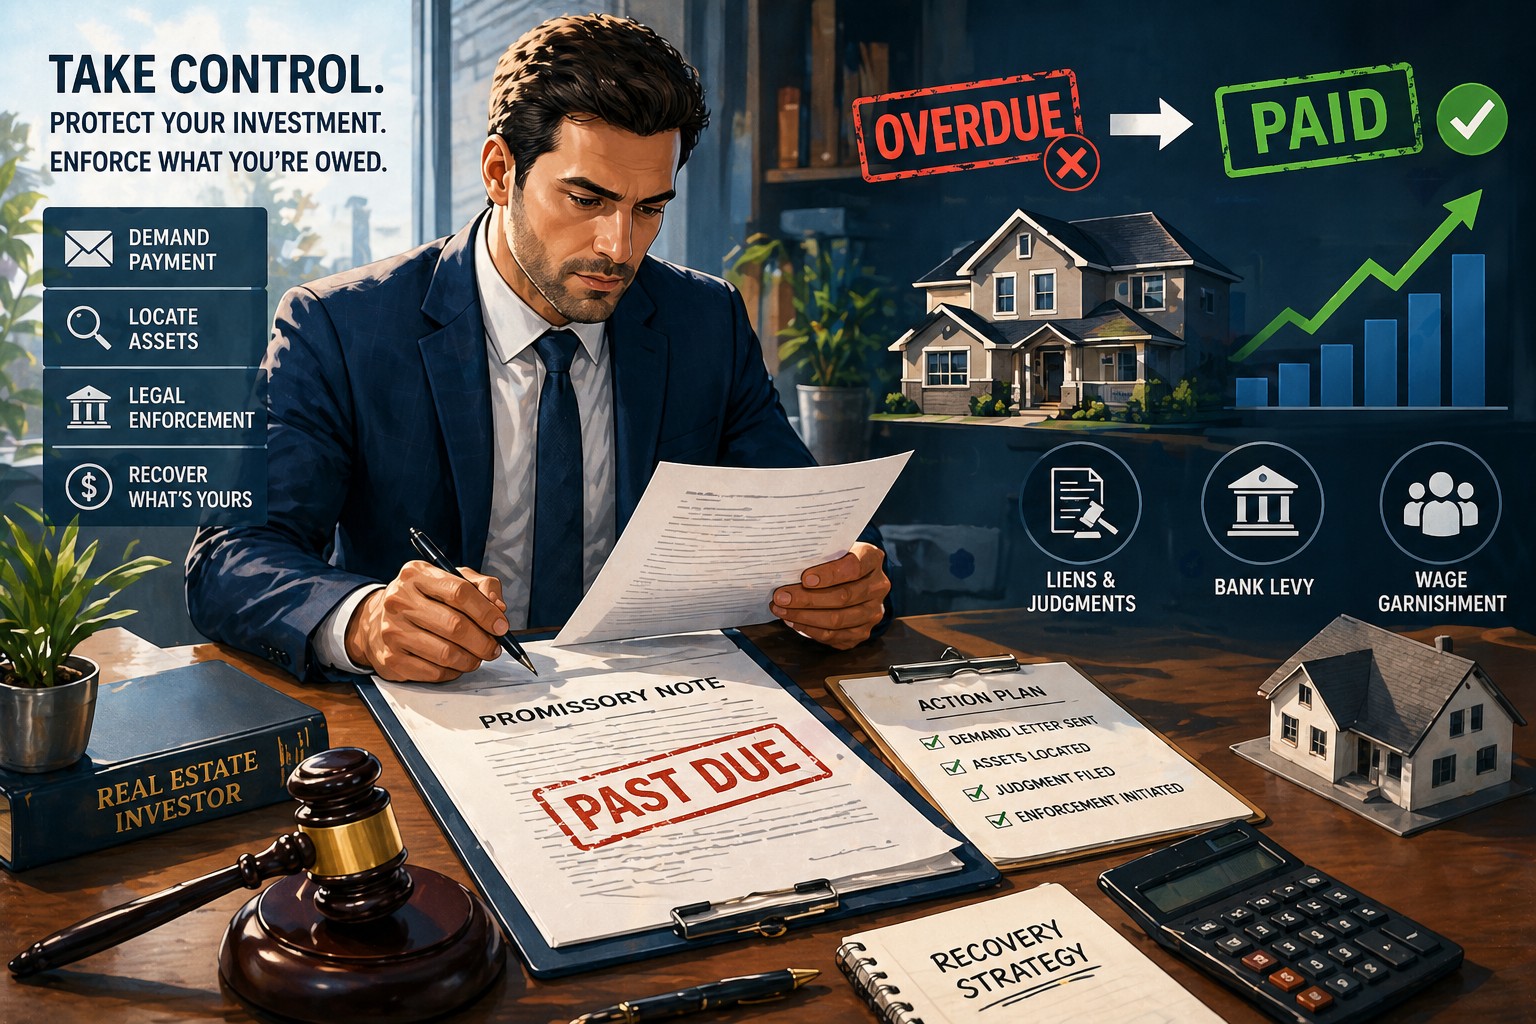
One of the most effective ways to begin is with a formal Demand for Payment letter. It might seem simple, but it plays a powerful role in setting the tone for everything that follows. This is your opportunity to clearly communicate that you are serious about enforcing the terms of your agreement.
A strong demand letter should be clear, direct, and professional. Include the exact amount that is overdue, the original due date, and a reference to the terms outlined in the promissory note. Set a firm deadline for payment and outline how the borrower can resolve the issue. When you send the letter through certified mail with a return receipt, you also create documented proof that the borrower received your notice.
You might be surprised how often this step alone prompts action. Many borrowers respond quickly once they realize that you are organized, prepared, and ready to escalate if necessary.
Asset Location and Skip Tracing
Before moving forward with legal action, it is important to understand the financial position of the borrower. This is where asset location, commonly known as skip tracing, becomes incredibly valuable. The goal is to identify where the borrower holds assets and whether they have the means to satisfy the debt.
This process can reveal ownership of additional real estate, active bank accounts, or steady income sources. Having this information allows you to focus your efforts where they matter most. Instead of guessing or pursuing options blindly, you can make informed decisions that increase your chances of recovery.
Working with experienced and reputable investigators can give you a clearer financial picture. This step helps you avoid unnecessary legal expenses and positions you for a more efficient and successful collection process.
The Legal Toolkit for Enforcement
If your demand letter does not lead to payment, it is time to take things to the next level. Pursuing a court judgment opens the door to powerful enforcement tools that can significantly improve your ability to collect.
One effective strategy is placing a lien on other properties owned by the borrower. This ensures that if they sell or refinance, your debt must be addressed before they can access the proceeds. Another option is a bank levy, which allows you to freeze and potentially collect funds directly from the borrower’s accounts.
In certain situations, wage garnishment may also be available. This enables you to collect a portion of the borrower’s income directly from their employer. Each of these tools increases pressure on the borrower and makes it much harder for them to ignore their obligations.
When used strategically, these legal options transform your position from passive creditor to active enforcer.
Mind the Statute of Limitations
Timing is critical when it comes to enforcing payment on a past-due note. Every state has its own statute of limitations that sets a deadline for filing a lawsuit related to debt collection.
If that deadline passes, your ability to take legal action may be lost. This can turn a recoverable asset into a permanent loss. That is why it is essential to act with urgency and awareness.
Take the time to review the laws that apply to your situation and confirm how much time you have left. Acting early preserves your rights and keeps all your options available. Waiting too long can significantly limit your ability to recover what you are owed.
Know When to Bring in an Expert
You do not need to handle this process alone. In fact, bringing in a professional can often make a significant difference in both speed and results. Commercial collections attorneys have the experience and knowledge needed to navigate the complexities of enforcing real estate notes.
They can manage every step, from filing the case to serving legal documents and negotiating with the borrower. Their understanding of local courts and property laws allows them to identify the most effective path forward for your specific situation.
An experienced attorney can also help you evaluate whether foreclosure is the right move. In many cases, their guidance leads to settlements that are both realistic and enforceable. Partnering with an expert can reduce stress, save time, and improve your overall outcome.
Regain Control Today
A delinquent real estate note does not have to mean defeat. It is simply a challenge that calls for a clear plan and decisive action. By starting with a strong demand, identifying the borrower’s assets, and using the legal tools available to you, you can move forward with confidence.
Stay focused, remain consistent, and approach the process with a professional mindset. Every step you take brings you closer to recovering your investment and strengthening your financial position. Now is the perfect time to take action, protect your capital, and set your business up for long-term success.
This post is generated by ChatGPT