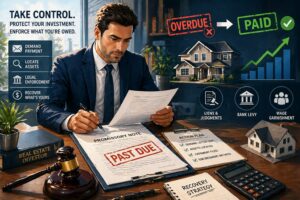
Your Florida beach rental was seller-financed like a dream, $250,000 note, clean paperwork, 7% interest, smooth monthly cash flow. Life was good. Then month three arrives… and nothing. No payment. No email. No explanation. Meanwhile, your IRS Form 1098 deadline is staring you down, and that calm confidence starts morphing into full-blown stress.
Sound familiar?
You’re not alone. In 2026’s higher-rate U.S. market, seller-financed real estate notes are powerful wealth-builders. But when buyers stop paying, that “passive income” can quickly feel very active, and very painful. The good news? You don’t need to panic. And you definitely don’t need to torch your deed of trust.
With the right strategy, most delinquencies can be resolved quickly, legally, and without dragging yourself through a courtroom marathon. From UCC acceleration to FDCPA-compliant demand letters and lightning-fast non-judicial foreclosures in places like Texas, investors are recovering up to 95% of balances within 60 days.
Ready to flip the power dynamic? Let’s walk through the 7 proven steps that can help you reclaim your cash flow, and your confidence.
Step 1: Laser-Audit Your Promissory Note
Before you send a single letter or make a single call, pull out your promissory note and deed of trust (or mortgage) and review them like a hawk.
You’re looking for:
- Grace periods (typically 10–15 days)
- Defined default triggers
- Late fee provisions (often 4–6% of the overdue amount)
- Acceleration clauses
- Escrow requirements
- Due-on-sale language
Under UCC §9-607, note holders generally have the right to demand the full balance after default if the contract allows it. That acceleration clause is your leverage.
In states like Texas, due-on-sale clauses can be especially powerful. If the borrower attempts to transfer the property, you may have grounds to call the full balance immediately.
Pro tip: Verify insurance coverage and property taxes. One Florida investor discovered unpaid insurance escrow during a routine audit and recovered over $8,000 in back charges within days.
Quick Audit Checklist:
- Complete payment history ledger (IRS compliant)
- Original signatures and notarization
- State-specific riders (for example, California anti-deficiency language)
- Escrow balance status
- ‘Hazard insurance verification
This step costs little to nothing if done yourself, or about $200 for a title search. Either way, knowledge is power. Once you know your rights, you can act decisively.
Step 2: Send a FDCPA-Compliant Demand Letter
Skip the casual text. This is business.
Send a formal demand letter via certified mail in compliance with the Fair Debt Collection Practices Act (15 U.S.C. §1692). Even if you’re not technically a third-party collector, following FDCPA standards protects you from missteps.
Your notice should clearly state:
- The amount overdue
- Accrued late fees
- Escrow shortages
- Cure deadline (typically 30 days)
- Acceleration warning
Sample language snippet:
“Pursuant to Paragraph 7 of the Promissory Note dated [date], you are currently in default in the amount of $[amount]. If this default is not cured by [date], the full unpaid principal balance may be accelerated.”
Send it immediately after the grace period expires.
In Florida, experienced investors report roughly 80% of borrowers cure the default once formal notice hits their mailbox. One Arizona investor sent a single certified letter to a ghosting flipper, and received a $50,000 wire transfer within two weeks. No lawsuit required.
Estimated cost: $50 certified mailing + $100 attorney review
Timeline: Day 1 after grace expiration
Professional tone + firm deadline = powerful motivator.
Step 3: Activate Late Fees and Escrow Enforcement
Now it’s time to apply contractual pressure.
If your note allows it, assess late fees according to the agreed percentage. Most states permit reasonable late charges between 4% and 6%. In some states like Florida, caps may apply.
Escrow defaults can be equally powerful. If taxes or insurance lapse, you may have independent grounds to declare default, even if the payment delay is short.
In non-judicial foreclosure states such as Texas, escrow violations can trigger faster enforcement pathways.
Many investors in 2026 are using professional servicing software with FedNow instant payment integration to automatically invoice, apply late fees, and track delinquencies. One Nevada note holder recovered $12,000 in accumulated fees after systematically enforcing terms instead of “letting it slide.”
Consistency matters. Borrowers respond when consequences are predictable.
Step 4: Hire a Licensed Note Servicer
Handling collections yourself might seem efficient, but errors can be expensive. IRS reporting (Forms 1098 and 1099-INT), escrow management, and compliance rules require precision.
Licensed, NMLS-regulated servicing companies typically charge $15–$25 per month, with setup fees around $300. In exchange, they provide:
- Professional payment tracking
- Escrow monitoring
- FDCPA-compliant notices
- Accurate year-end tax reporting
- Clear servicing history (which increases note resale value)
Clean servicing records can boost note value by up to 20% on resale.
One Florida investor recovered a $100,000 delinquent Orlando note after transferring servicing and initiating formal acceleration. The structure alone changed borrower behavior.
Think of it as upgrading from DIY bookkeeping to institutional-grade asset management.
Step 5: File a Notice of Default (NOD)
If 30 days pass with no cure, it’s time to escalate.
The Notice of Default process varies by state:
- Texas: Trustee posts notice at courthouse; roughly 45-day cure period
- Florida: Judicial foreclosure filing begins (legal fees typically $2,000+)
- California: NOD recorded; anti-deficiency rules may limit recovery
Typical Escalation Timeline
| Days Past Due | Action | Avg. Cost |
|---|---|---|
| 30 | Notice of Default | ~$500 |
| 60 | Trustee Sale Notice | ~$1,500 |
| 90+ | Foreclosure Sale | $5,000+ |
In non-judicial states, timelines are dramatically faster. A Texas ranch note holder completed a trustee sale in 120 days and netted 102% of principal due to accrued fees and bidding competition.
Judicial states move slower, but often still resolve before trial if borrower refinances to avoid foreclosure.
Step 6: Deploy UCC Acceleration and Repossession Rights
Under UCC §9-609, secured creditors may repossess collateral without judicial process if it can be done peacefully. In real estate contexts, this typically operates through trustee foreclosure sales in non-judicial states.
Acceleration means the entire unpaid principal becomes immediately due.
Pair this with credit bureau reporting (where applicable and compliant). Studies show that formal credit reporting can increase borrower cure rates by up to 70%.
Another effective strategy? “Cash for keys.” Offer a modest relocation incentive (for example, $3,000–$5,000) in exchange for a clean surrender of the property. It often costs less than extended litigation and reduces damage risk.
A Georgia investor accelerated a $75,000 delinquent note and offered structured payoff options. The borrower refinanced within weeks to avoid public sale.
Acceleration is leverage. Use it strategically, not emotionally.
Step 7: Sell or Restructure the Note
If enforcement becomes inefficient, consider exit strategies.
Option 1: Sell the Note
Performing notes with strong documentation can sell for 80–95% of face value. Even delinquent notes can command respectable pricing if collateral equity is strong.
In 2026, AI-driven valuation tools are helping investors price distressed notes accurately. One Phoenix investor sold a troubled note and still walked away with a $90,000 gain due to underlying property appreciation.
Option 2: Restructure
Sometimes the smarter play is modification:
- Temporary interest reduction
- Balloon extension
- Forbearance plan
- Re-amortization
Restructuring keeps cash flowing and avoids foreclosure costs. Many borrowers who fall behind due to temporary setbacks can recover with structured flexibility.
Your goal isn’t punishment, it’s performance.
Prevention Power Moves
Winning enforcement battles starts before the first payment is ever missed.
Protect yourself upfront with:
- Automatic ACH debit clauses
- Personal guarantees
- Adequate down payments
- Title insurance
- Clear escrow requirements
- Strong acceleration language
Well-drafted Texas-style deeds of trust are especially enforcement-friendly. Solid documentation reduces headaches later.
Quick Recap
| Step | Key Action | Typical Success Impact |
|---|---|---|
| 1 | Audit Documents | Foundational leverage |
| 2 | Demand Letter | ~80% cure rate |
| 5 | NOD Filing | Forces resolution |
| 7 | Sell/Restructure | Preserves capital |
Always consult local counsel, foreclosure and deficiency rules vary dramatically by state.
Reclaim Your Note. Reignite Your Empire.
There you have it, seven proven, strategic steps to enforce past-due real estate notes without sacrificing your asset.
From Florida beach rentals to Texas ranch properties, investors in 2026 are reclaiming millions in delinquent balances by acting quickly, staying compliant, and using leverage intelligently.
One missed payment doesn’t define your portfolio. How you respond does.
So take a breath. Pull the file. Send the letter. Activate your rights.
And if you’ve got a wild recovery story of your own, share it. The note-investing community thrives on shared wins.
Your cash flow comeback starts now.
This post is generated by ChatGPT